Short answer: a tenant improvement allowance (TIA) is money a landlord gives a tenant to fit out leased space. When the tenant owns the improvements, the landlord records the TIA as a lease incentive asset. It then amortizes that asset in a straight line over the lease term as a reduction of rental income. The tenant treats the TIA as a lease incentive that lowers its right of use asset under ASC 842 or IFRS 16. If the lease ends early, the landlord writes off the balance left on the books.
The cash goes out in one week. The accounting runs for years. That gap is where TIA errors live. One team expenses the payment. Another capitalizes it and then forgets it when the tenant leaves. This guide covers the full cycle, from the lease clause to the last month of amortization. It includes journal entries, a schedule and a worked example with real numbers.
What a tenant improvement allowance is
A TIA is a lease incentive. It closes the gap between the base building and the space a tenant needs to open for business. Landlords offer it to win or keep a tenant. A good tenant on a long lease is often worth more than a vacant floor or a weaker tenant at a lower rent.
The lease sets the amount. It can be a fixed sum, a rate per square foot or a cap against invoices. The lease also says when the money is paid, what it can fund and what happens to any unused balance.
What a TIA can and cannot pay for
| Usually allowed | Usually excluded |
|---|---|
| Partitions, demising walls and ceilings | Loose furniture and movable equipment |
| Floor finishes and lighting fixed to the building | Artwork and decor |
| Electrical work and data cabling | Moving and relocation costs |
| HVAC changes and plumbing | Costs incurred before the lease is signed |
| Restrooms and kitchens inside the space | Project fees above the agreed cap |
Some leases do allow furniture or signage. Read the clause. Claims for costs outside the clause cause many TIA disputes. The split also matters for the tenant's own books. Fixed improvements are capitalized as leasehold improvements. Loose furniture goes on a separate equipment schedule.
TIA and leasehold improvements: the difference
The two terms get mixed up all the time. The TIA is the funding. The leasehold improvement is the physical asset the funding pays for.
| Point | Tenant improvement allowance | Leasehold improvement |
|---|---|---|
| What it is | Cash or credit from the landlord | The built works inside the space |
| Who provides it | Landlord | Tenant, funded in part by the TIA |
| Landlord books | Lease incentive asset, amortized against rent | Only when the landlord owns the works |
| Tenant books | Lowers the right of use asset | Fixed asset, amortized over the shorter of useful life and lease term |
| At lease end | Fully amortized | Stays with the building or is removed under the lease |
How TIAs are structured in a lease
The structure drives the timing of every entry. Four forms cover nearly every commercial deal.
1. A fixed sum
The lease names a total, such as $200,000. The tenant submits invoices or a completion certificate and the landlord pays. The tenant funds any overrun. The lease decides whether an unused balance is kept or lost.
2. A rate per square foot
This is common in office and retail leases. A rate of $65 per square foot on 3,000 square feet gives $195,000. It ties the incentive to the size of the space and makes deals easy to compare.
3. Reimbursement against costs
The landlord repays approved costs up to a cap. The tenant sends invoices, receipts and sometimes a cost report. This gives the landlord a view of how the money is spent. The draw request steps are set out in our guide to the tenant improvement build out process.
4. A rent credit
The landlord gives free or reduced rent in place of cash. The economic cost can be similar, yet no cash changes hands. The accounting follows straight line rent, covered below. For a side by side of the two options, read TI allowance vs rent abatement.
Who owns the improvements decides the accounting
Ask this before you post anything. Who owns the improvements, and who carries the risk of cost overruns? If the tenant owns them, the landlord's payment is a lease incentive. If the landlord owns them, the landlord has bought a building improvement. Write the answer into the lease file when the lease is signed. Do not leave it for the auditors to settle a year later. When the facts are mixed, agree the treatment with your auditor.
Landlord accounting for a tenant improvement allowance
Cash paid to the tenant
The payment is capitalized. It is not expensed when paid. The asset is then amortized in a straight line over the lease term as a reduction of rental income. The cost is matched to the rent it was paid to secure.
| Event | Debit | Credit |
|---|---|---|
| TIA paid to the tenant | Lease incentive asset | Cash or accounts payable |
| Each month of the lease term | Rental income | Lease incentive asset, or its accumulated amortization account |
| Lease ends early | Loss on lease termination | Lease incentive asset, for the balance left |
If the TIA is paid in draws, record each draw when it is paid. Amortization starts when the lease term starts. A draw paid before that date waits on the balance sheet until then.
The lease term means the committed term. Add option periods only when the tenant is reasonably certain to use them. Do not use the useful life of the works or the life of the building.
When the landlord owns the improvements
Some works stay with the building, such as an upgraded HVAC system or new restrooms. The landlord capitalizes these as building improvements on its fixed asset register. They are depreciated over their useful life to the landlord. Works that suit only one tenant may have little value after that lease ends, which can shorten that life. This is fixed asset accounting, not lease incentive accounting. The usual fixed asset depreciation rules apply.
When the TIA is given as free rent
Free rent months do not reduce revenue in those months. The landlord adds up the total rent due over the term and spreads it evenly. In the early months, revenue runs ahead of cash. The gap builds a straight line rent receivable. RIOO explains the method on its straight line rent page.
Keep straight line rent and TIA apart
Both reduce or adjust rental income over the lease term. They still need separate accounts. Each one reacts in its own way when a lease ends early, and each one shows up in its own place on the balance sheet. Merging them into one balance makes the early exit entry hard to get right.
Under IFRS 16
The result is close to the US treatment. A lessor in an operating lease deducts lease incentives from the lease payments. It then recognizes the net income in a straight line over the term.
Tenant accounting under ASC 842 and IFRS 16
For the tenant, a TIA lowers the net cost of the space. It is not income when received.
Under ASC 842, the tenant books a right of use asset and a lease liability at commencement. A TIA received at or before commencement reduces the right of use asset. A TIA still to be received reduces the lease payments, so it lowers both the liability and the asset. The benefit then flows through the income statement as a lower lease cost over the term. IFRS 16 works the same way.
The tenant also capitalizes the fitout it paid for as leasehold improvements. These are amortized over the shorter of their useful life and the remaining lease term.
Older leases may still carry ASC 840 balances. Under that standard, a TIA was booked as deferred rent and released against rent expense. Companies that moved to ASC 842 with the modified retrospective method may still see those balances folded into opening right of use assets.
A US tax note for retail tenants
Under Section 110 of the Internal Revenue Code, a tenant in retail space can leave a qualified lessee construction allowance out of gross income. Retail space covers businesses that sell goods or services to the general public, including many service firms. The lease must run 15 years or less and must state that the allowance is for building or improving the space. The money must be spent in the year received on qualified long term real property at that space. That property must revert to the landlord when the lease ends, and the landlord treats it as its own property. The conditions are set out in the Treasury regulations under Section 110. Confirm the details with your tax adviser.
A worked example: $195,000 over 60 months
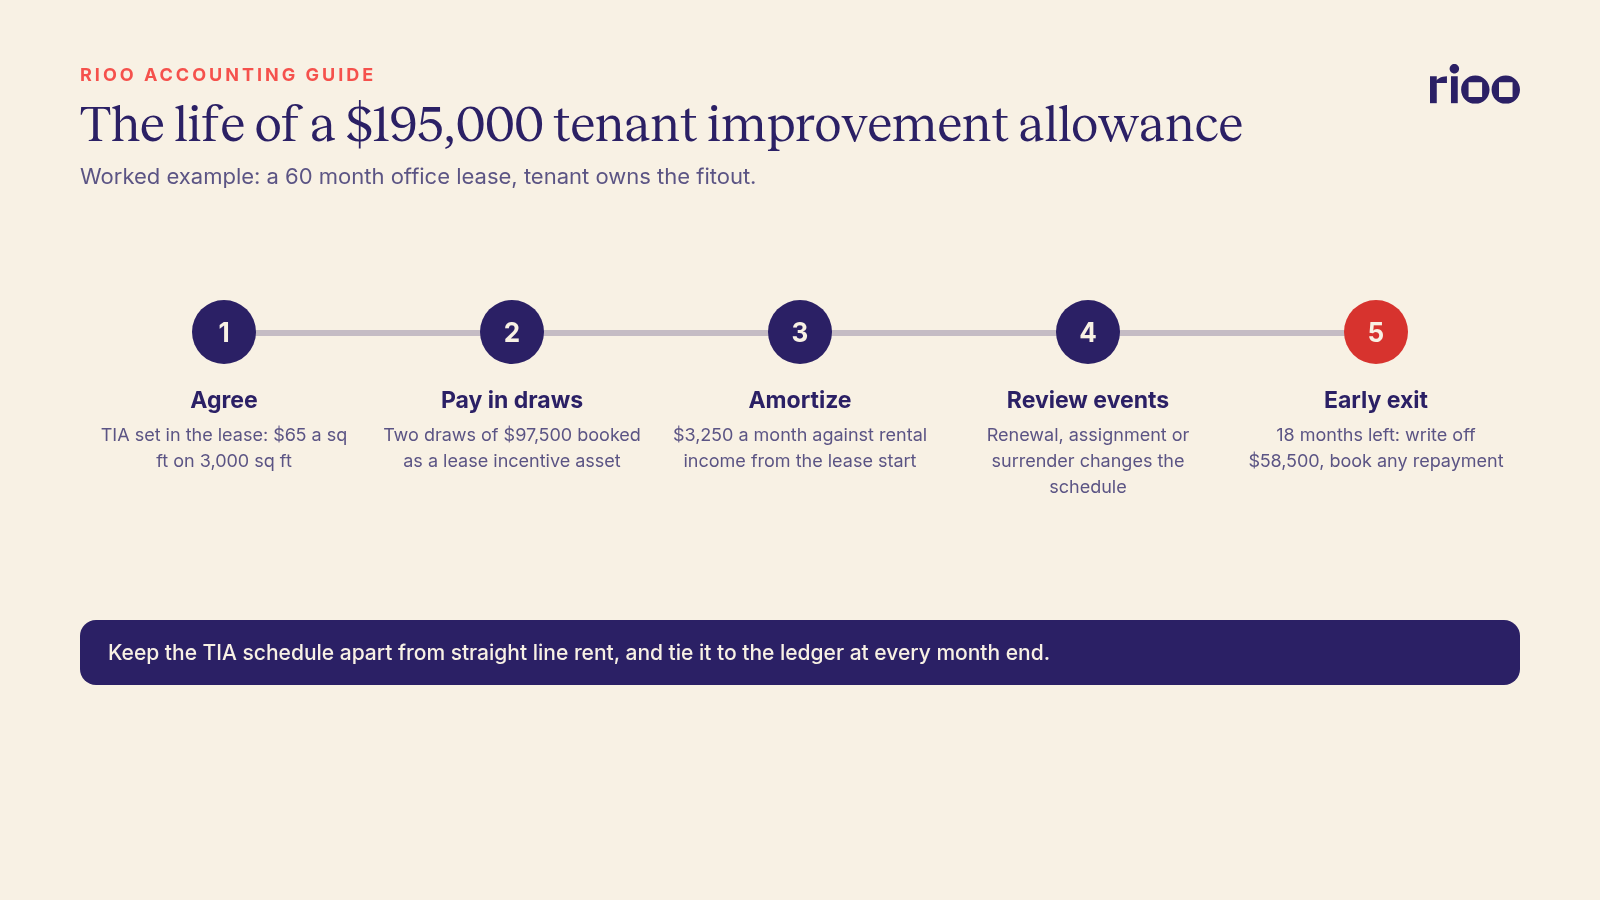
A landlord signs a 60 month office lease for 3,000 square feet. Base rent is $90,000 a year, or $7,500 a month. The TIA is $65 per square foot, so $195,000. The tenant owns the fitout. The landlord pays the TIA in two draws of $97,500 each, one at the halfway point of the build and one at completion. Both draws land before the lease term starts.
Landlord, at each draw: debit lease incentive asset $97,500 and credit cash $97,500. The asset reaches $195,000 before the lease term starts.
Landlord, each month: $195,000 divided by 60 gives $3,250. Debit rental income $3,250 and credit the lease incentive asset $3,250.
Each year the tenant pays $90,000 in cash rent. The landlord books $39,000 of amortization. Net rental income is $51,000 a year.
| Month | Opening balance | Amortization | Closing balance | Amortized to date |
|---|---|---|---|---|
| 1 | $195,000 | $3,250 | $191,750 | $3,250 |
| 2 | $191,750 | $3,250 | $188,500 | $6,500 |
| 12 | $159,250 | $3,250 | $156,000 | $39,000 |
| 24 | $120,250 | $3,250 | $117,000 | $78,000 |
| 42 | $61,750 | $3,250 | $58,500 | $136,500 |
| 60 | $3,250 | $3,250 | $0 | $195,000 |
Tenant view: the fitout costs $240,000. The tenant capitalizes $240,000 of leasehold improvements. The works have a 10 year life, yet the lease is 5 years. So the tenant amortizes them over 60 months at $4,000 a month. The $195,000 TIA lowers the right of use asset. Total rent over the term is $450,000. Less the $195,000 incentive, that leaves $255,000. The straight line lease cost is $51,000 a year.
Early exit: the tenant leaves at the end of month 42. Eighteen months are left. The balance is $3,250 times 18, which is $58,500. The landlord debits loss on lease termination $58,500 and credits the lease incentive asset $58,500. The lease says the tenant must repay the unamortized TIA. When the $58,500 arrives, the landlord records it as termination income on its own line. Both entries stay gross. This assumes the exit takes effect when it is agreed. If it is agreed months ahead, the modification rule under early termination below applies.
Building the amortization schedule
Every TIA on the balance sheet needs its own schedule. Set it up before the first period closes.
| Field | What it holds |
|---|---|
| Lease reference | Property, tenant and lease ID |
| TIA amount | Total paid or committed |
| Start date | Lease term start, when amortization begins |
| End date | Lease expiry, when the balance must reach zero |
| Term in months | Number of periods |
| Monthly charge | TIA amount divided by the term in months |
| Period rows | Opening balance, charge and closing balance for each month |
| Net carrying value | TIA amount less amortization to date |
The net carrying value is the figure that matters at an early exit. It is the amount to write off and the starting point for any recovery claim.
Common schedule errors
- Wrong start date. Start when the lease term begins. Do not start on the payment date, the completion date or the first day of the financial year.
- Wrong term. Use the lease term. A 5 year lease with a fitout that lasts 10 years is still amortized over 5 years.
- No update after a lease event. Renewals, exits and assignments all need a review of the balance.
- No tie to the ledger. The ledger balance must equal the schedule's net carrying value at every month end. A gap means a missed payment or a wrong journal.
What happens at lease events
The TIA balance moves with the lease. Each event needs its own response.
Renewal
A renewal often counts as a change to the existing lease. The balance left is then spread over the new, longer term. This lowers the monthly charge from that point on. Some renewals are treated as a new lease. Assess the terms when the renewal is signed. A new TIA for the renewal term is a separate asset with its own schedule.
Early termination
This is the event with the biggest effect. Once the rent stream ends, there is no basis to keep the asset. If the exit takes effect when it is agreed, write off the balance in that period. Book any repayment from the tenant as income on its own line. If the termination is agreed ahead of the exit date, ASC 842 usually treats it as a lease modification. The balance left and any termination payment are then recognized over the shortened term up to the exit date. Agree the treatment with your auditor. The early lease termination accounting guide covers settlement entries in more detail.
Assignment
When a tenant assigns the lease, the TIA balance usually stays as it is. The incentive runs with the lease. The schedule carries on. A new TIA offered to the incoming tenant is booked separately.
Surrender by agreement
If the landlord accepts a surrender, treat it like an early exit, including the timing rule above. Record any agreed TIA repayment as part of the same review.
Restoration duties at lease end
Many leases require the tenant to restore the space at the end. If works funded by the TIA must be removed, the tenant may need to recognize a restoration liability once the works are in place. The matching cost is usually added to the related asset and expensed over its life. Agree the treatment with your auditor. Read more in our guide to make good in a commercial lease.
TIA in NOI, valuation and reporting
Two views of NOI are in common use. In GAAP rental income, the amortization lowers income, so reported NOI falls. In a cash view, owners treat the TIA as a capital cost below NOI. Both are fine. State which one your reports use.
Either way, effective rent is lower than headline rent. Take a building with $1,200,000 of contracted rent and $120,000 a year of incentive amortization. Its effective rent is $1,080,000. A buyer who prices it on $1,200,000 will overstate the yield. Valuers often deduct unpaid TIA commitments from value too.
Reports every portfolio needs
- TIA balance by property and lease. Original amount, amortized to date, net carrying value and months left.
- Monthly charge by property. It feeds the property income statement and must tie to the ledger.
- Balance at risk by expiry window. Group balances by leases ending in 12 months, 12 to 24 months and later. Large balances on short leases flag recovery risk early.
- Committed but unpaid TIA. Signed leases with draws still to come. These belong in the cash flow forecast, apart from the asset balance.
- Schedule to ledger reconciliation. Clear any variance before the period closes.
Scale makes this matter. A portfolio with 50 commercial leases and an average TIA of $150,000 carries $7.5 million of incentive assets. Every one of them is amortizing and reacting to lease events.
Common TIA accounting mistakes
- Expensing the payment. It overstates costs in the first year and understates them in every year after.
- Amortizing over the wrong period. Using the building life or the fitout life leaves a balance at lease end that nobody can explain.
- Booking the TIA as income on the tenant side. Under ASC 842 and IFRS 16 it lowers the right of use asset.
- Losing the link to lease events. The schedule keeps running after the tenant has left, or past the old expiry after a renewal.
- Missing committed TIA. Unpaid commitments drop out of the cash forecast and surprise treasury when the invoice lands.
- Netting the write off and the recovery. A zero balance hides what happened. Auditors will ask for both entries.
- Leaving the repayment clause out of the lease abstract. If nobody records it, nobody claims it at termination.
Documents to keep
- At signing: the lease with the TIA amount, draw conditions and any forfeiture or repayment terms, plus the schedule and the first journal with its source document.
- During the term: invoices, approvals and payment proof for each draw, monthly schedule reconciliations and any amendments that change the TIA.
- At lease events: renewal, termination and assignment papers that state what happens to the balance.
- At expiry: proof the balance reached zero and a final entry for any rounding left over.
Where RIOO fits
RIOO supports lessor lease accounting on NetSuite. That covers lease classification, straight line rental income, lease incentives, modifications and the data for disclosures. These are calculated from the same lease records your property team manages. Improvements the landlord owns sit in NetSuite Fixed Assets. RIOO is designed for landlords, so tenant side right of use accounting is out of scope. See RIOO lease accounting.
Frequently asked questions
What is a tenant improvement allowance?
It is money a landlord gives a tenant to fit out leased commercial space. It is a lease incentive, agreed with the rent and term.
Is a tenant improvement allowance an asset or an expense?
For the landlord, a TIA paid for works the tenant owns is an asset. It is amortized against rental income over the lease term. For the tenant, it lowers the right of use asset.
How is a TIA amortized?
In a straight line over the lease term. Take the TIA amount and divide it by the months in the term. A $195,000 TIA on a 60 month lease gives $3,250 a month.
When does TIA amortization start?
When the lease term starts. A TIA paid before that date waits on the balance sheet until then.
Is TIA amortization an expense or a reduction of rental income?
For the landlord, it is a reduction of rental income. It reflects a cost of getting the lease, not a running cost of the building.
What happens to the TIA if the tenant leaves early?
The landlord writes off the balance left in the period the exit takes effect. Any repayment the lease requires is booked as income on its own line. When the exit is agreed well in advance, the balance is usually spread over the shortened term instead.
Is a TIA the same as a leasehold improvement?
No. The TIA is the money. The leasehold improvement is the built work it pays for. Each has its own accounting.
How should committed but unpaid TIA be treated?
Track it as a future cash outflow and show it in the cash flow forecast. Capitalize it when it is paid or when the duty to pay becomes unconditional.